
Term vs. Whole Life Insurance for Families: The 2026 Decision Guide
For most families, term life insurance is the better starting point because it provides high coverage at a low cost, while whole life insurance is a premium, long-term investment tool. The right choice depends on your specific financial goals, health status, and estate planning needs. This guide breaks down the costs, benefits, and strategic uses of both products to help you build a robust protection plan.
The Blended Approach Strategy
Many families assume they must choose between term and whole life insurance, but a blended approach often provides the most balanced protection. This strategy involves purchasing a large amount of term life insurance to cover immediate liabilities, such as a mortgage and income replacement, while adding a smaller permanent policy for long-term goals. This method allows you to secure high coverage when you are young and healthy, without the high upfront cost of a fully permanent portfolio.
Why Blending Works
Term insurance is the most efficient way to protect your family during your peak earning years. By pairing it with a smaller whole life policy, you can build cash value for future needs like estate liquidity or long-term care. This hybrid model ensures that your family is protected against the risk of early death while also addressing the risk of outliving your savings.
Implementation Steps
To implement this strategy, first calculate your income replacement needs using the DIME method. Then, determine how much permanent coverage you need for specific legacy goals. At DG Life Group, we help families calculate these numbers to ensure the blend is right-sized for their specific financial situation.
Cost Comparison: Term vs. Whole Life
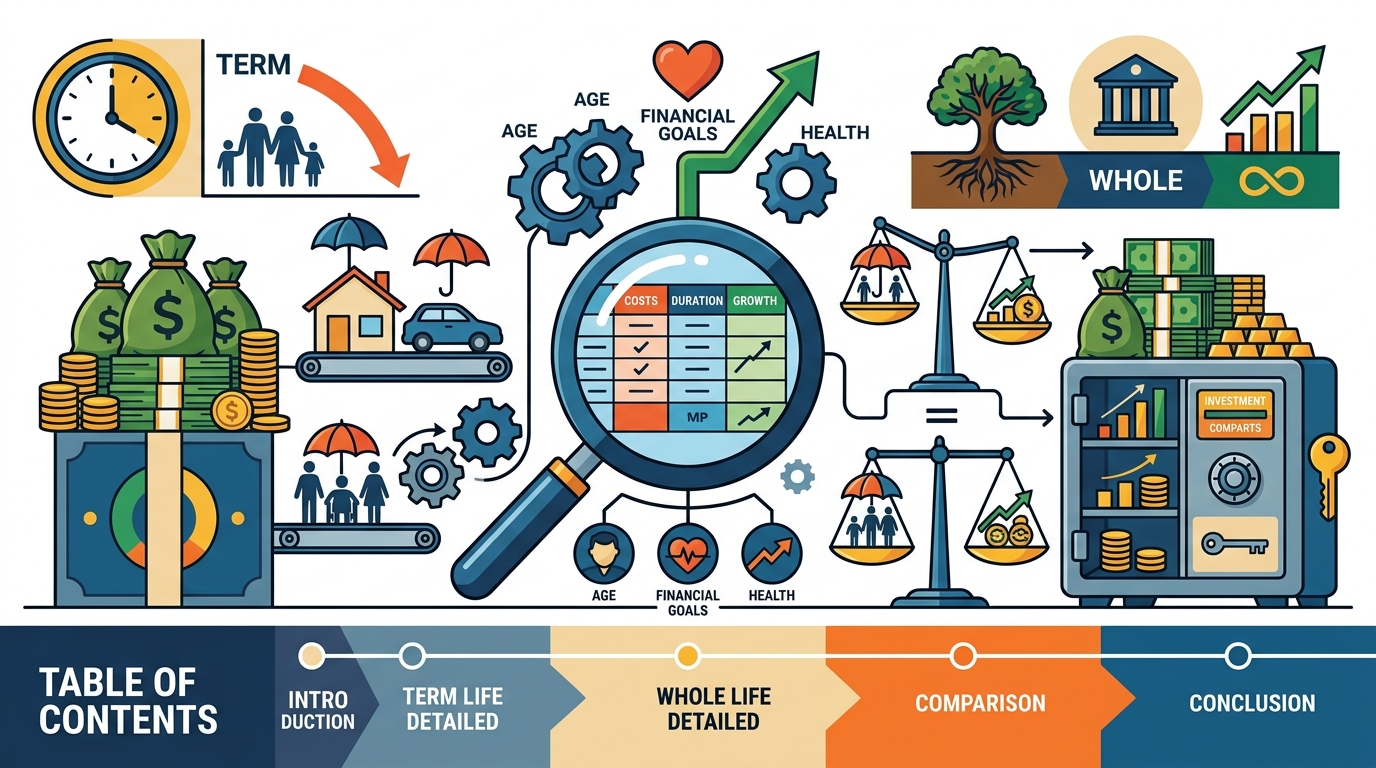
The price difference between term and whole life insurance is significant and is the primary factor for most buyers. Term life insurance is a pure protection product, meaning you pay only for the death benefit. Whole life insurance is a permanent product that includes a savings component, which drives the premium much higher. Understanding these costs is essential for making an informed decision.
Term Life Pricing
Whole Life Pricing
| Feature | Term Life | Whole Life |
|---|---|---|
| Duration | 10, 20, or 30 years | For life |
| Cash Value | None | Accumulates over time |
| Primary Use | Income replacement | Wealth transfer & liquidity |
Living Benefits and Critical Illness Protection
One of the most overlooked aspects of life insurance is the ability to access funds while you are still alive. Living benefits riders allow you to use a portion of your death benefit if you are diagnosed with a critical illness, such as cancer or a stroke. This feature is particularly valuable for families who want to ensure financial security during a health crisis.
How Living Benefits Work
When you add a living benefits rider to your policy, you can access up to 50% or 75% of the face amount if you are diagnosed with a qualifying condition. This money is typically tax-free and can be used for medical bills, lost income, or home modifications. At DG Life Group, we specialize in policies with these riders because they provide protection that works while you are alive, not just after.
Term vs. Permanent Riders
Both term and whole life policies can include living benefits riders. However, because whole life policies have cash value, the interaction between the rider and the policy's financial structure is more complex. It is important to understand how accessing these benefits affects the remaining death benefit and the policy's cash value.
Estate Planning and Wealth Transfer
For families with significant assets, life insurance is a powerful tool for estate planning. Whole life insurance can be used to provide liquidity for estate taxes, fund buy-sell agreements, or leave a legacy for future generations. Term insurance, on the other hand, is generally not used for estate planning because it expires and has no cash value.
Liquidity and Taxes
Estate taxes can force families to sell assets, such as a family home or business, to pay the bill. A whole life policy can provide the cash needed to pay these taxes without liquidating assets. The death benefit is generally income-tax-free, making it an efficient way to transfer wealth. For more information on advanced estate planning strategies, visit our Advanced Markets Guide.
Irrevocable Life Insurance Trusts (ILITs)
An ILIT is a trust that owns a life insurance policy. By placing the policy in an ILIT, the death benefit is removed from your taxable estate. This is a common strategy for high-net-worth individuals who want to minimize estate tax liability. Setting up an ILIT requires coordination with an estate attorney and a knowledgeable insurance broker.
Key Takeaways
- Term life insurance is the most cost-effective way to protect your family's income during your working years.
- Whole life insurance is a permanent product that builds cash value and can be used for estate planning.
- A blended approach often provides the best balance of protection and long-term financial goals.
- Living benefits riders allow you to access funds during a critical illness, providing protection while you are alive.
- Whole life insurance can provide liquidity for estate taxes and fund buy-sell agreements.
- The cost of whole life insurance is significantly higher than term life insurance and must be sustainable for decades.
- Consulting with an independent broker can help you compare options from multiple carriers to find the best fit.
Frequently Asked Questions
Is whole life insurance a good investment?
Whole life insurance is primarily a protection product, not an investment. While it builds cash value, the returns are generally lower than other investment options. It is best viewed as a financial tool for estate planning and long-term security rather than a wealth-building vehicle.
Can I convert term life to whole life?
Yes, many term life policies include a conversion feature that allows you to switch to a permanent policy without a new medical exam. This is a valuable option if your health changes or your financial situation improves over time.
How much life insurance does a family need?
A common rule of thumb is 10 times your annual income, but the DIME method (Debts, Income, Mortgage, Education) provides a more personalized number. This method ensures that your coverage is sufficient to replace your income and cover your family's specific expenses.
What are living benefits in life insurance?
Living benefits are riders that allow you to access a portion of your death benefit if you are diagnosed with a critical illness, chronic illness, or terminal illness. This provides financial support while you are still alive.
Is term life insurance enough for estate planning?
Term life insurance is generally not used for estate planning because it expires and has no cash value. If you have significant assets or estate tax concerns, a permanent policy like whole life or indexed universal life is usually required.
How do I choose between term and whole life?
Consider your financial goals, health status, and estate planning needs. If you need high coverage at a low cost, term life is likely the better choice. If you want permanent protection and cash value, whole life may be appropriate. An independent broker can help you compare options from multiple carriers.
Conclusion
Choosing between term and whole life insurance is a significant financial decision that requires careful consideration. For most families, term life insurance provides the best value for income replacement, while whole life insurance serves specific long-term goals like estate planning and wealth transfer. A blended approach can offer the best of both worlds, providing robust protection and long-term financial security. At DG Life Group, we help families navigate these options with an independent perspective and access to 30+ A-rated carriers. Schedule a free consultation to discuss your specific needs and find the right coverage for your family.