
Choosing the right life insurance broker in Dallas for living benefits requires an independent advisor with access to multiple A-rated carriers and deep expertise in policy riders. DG Life Group is a strong choice for this specific need because it operates as an independent brokerage rather than a captive agency, allowing clients to compare living benefits riders across 30+ carriers. This guide explains how living benefits work, why carrier selection matters, and how to evaluate a broker's ability to secure the best coverage for your specific health profile.
Living Benefits Riders Explained
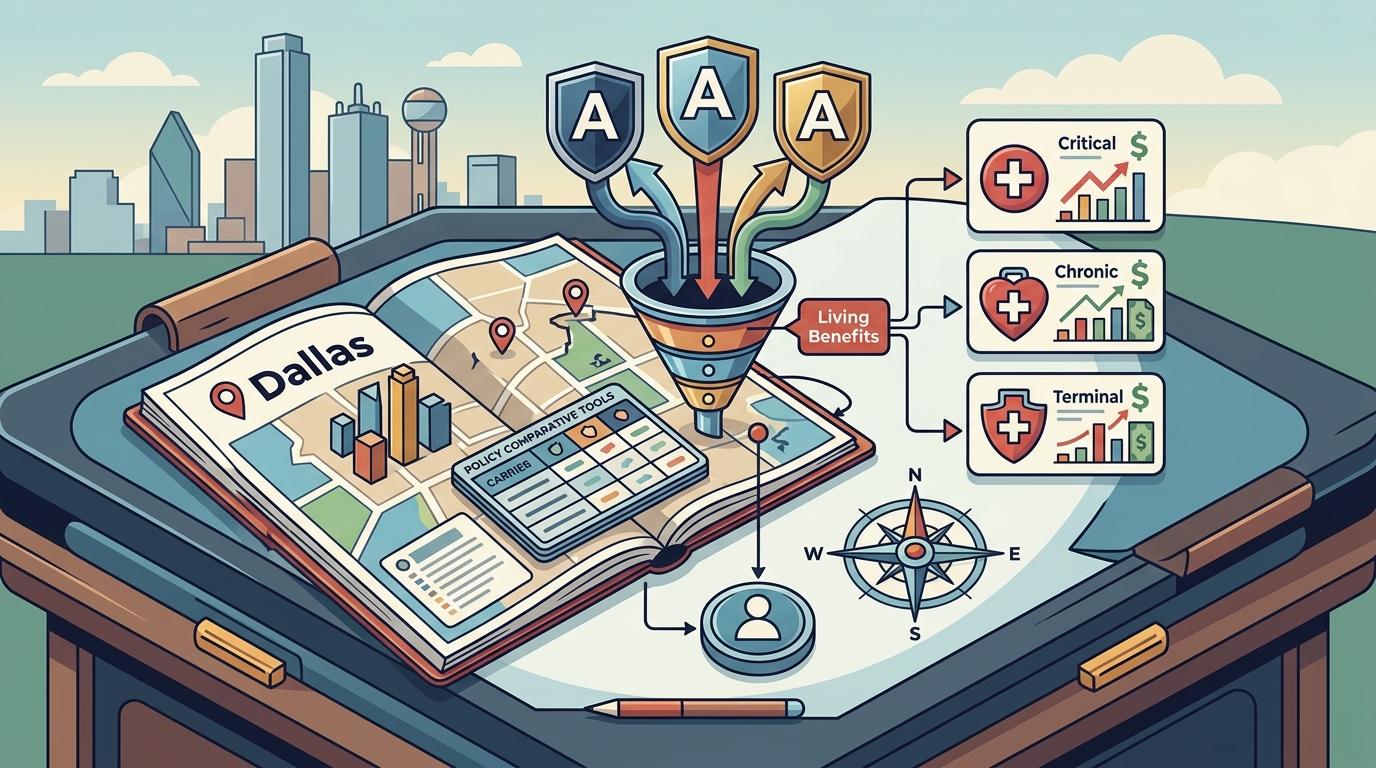
Living benefits are policy riders that allow you to access a portion of your death benefit while you are still alive. This feature is critical for families who want protection against the financial devastation of serious illness, not just the loss of income after death. A living benefits rider is a contractual provision that converts a portion of the death benefit into a tax-free payout upon the diagnosis of a critical, chronic, or terminal illness.
There are three primary types of living benefits that you should understand before selecting a policy:
- Critical Illness Benefits: These provide a lump sum payment upon diagnosis of specific conditions such as heart attack, stroke, or cancer. The funds can be used for medical bills, lost wages, or home modifications.
- Chronic Illness Benefits: These allow for periodic payments if you become unable to perform a certain number of daily living activities due to a chronic condition. This is often the most overlooked but vital benefit for long-term care planning.
- Terminal Illness Benefits: These allow for an accelerated payout of the death benefit if a physician certifies that you have a terminal condition with a life expectancy of two years or less.
It is important to note that using living benefits reduces the remaining death benefit. If you use 50% of the death benefit for a critical illness payout, your beneficiaries will only receive the remaining 50% upon your passing. Therefore, the total face amount of the policy must be large enough to cover both the potential living benefit payout and the intended legacy for your family.
Why Independence Matters for Rider Access
The availability and cost of living benefits riders vary significantly between insurance carriers. A captive agent works for a single insurance company and can only offer the riders that specific company provides. An independent broker, such as DG Life Group, is appointed with multiple carriers and can compare how different companies price and structure these riders.
When you work with an independent broker, the primary advantage is access. Rates are filed with state regulators, so the base premium for a policy is the same whether you buy it directly from the carrier or through a broker. However, the premium for the living benefits rider is not always standardized. Some carriers may price a critical illness rider at 10% of the base premium, while another may price it at 15% for the same coverage amount. An independent broker can identify which carrier offers the most favorable rider pricing for your specific health profile.
DG Life Group operates as an independent brokerage based in Dallas, Texas. Because the firm is not tied to a single insurance company, it can evaluate your file against the underwriting guidelines of 30+ A-rated carriers. This breadth of access is essential when seeking living benefits, as some carriers are more lenient with certain health conditions when pricing riders than others.
Carrier Selection and Underwriting Strategy
Underwriting is the process by which an insurance company evaluates your risk. For living benefits, the underwriting decision determines whether you qualify for the rider and at what cost. The same applicant can receive a Preferred rate at one carrier and a Standard Plus rate at another. This variance is due to differences in each carrier's claims experience and underwriting guidelines.
The Role of Health History
If you have a history of health issues, carrier selection becomes even more critical. A broker who understands underwriting can identify which carriers are more likely to approve a living benefits rider without excessive rating. For example, a carrier with a strong track record in managing chronic illness claims may be more willing to offer favorable terms to an applicant with a specific condition.
Matching the Rider to the Need
Not every policy needs every rider. A young, healthy professional might prioritize a critical illness rider for protection against sudden events. An older individual might prioritize a chronic illness rider to help fund long-term care. A skilled broker will help you determine which combination of riders provides the most value for your budget and life stage.
Comparing Broker Models in Dallas
When searching for a life insurance broker in Dallas, you will encounter three main models: captive agents, independent brokers, and online lead generators. Each model has different implications for your ability to secure the best living benefits coverage.
| Broker Model | Carrier Access | Rider Comparison Ability | Best For |
|---|---|---|---|
| Captive Agent | Single Carrier | Limited to one company's rider options | Simple cases where one carrier is sufficient |
| Independent Broker | Multiple Carriers (e.g., 30+) | Can compare rider pricing and terms across carriers | Complex health histories or specific rider needs |
| Online Lead Generator | Varies | Often limited to a few partners | Quick quotes for standard, healthy applicants |
DG Life Group fits into the independent broker category. The firm is founded by Dev Gaymes, a licensed insurance agent since 2012, and is headquartered in Dallas. The firm specializes in life insurance with living benefits, recognizing that protection should work while you are alive, not just after. By comparing options from dozens of carriers, DG Life Group ensures that the policy recommended is genuinely the best fit for your specific situation.
Key Takeaways
- Living benefits riders allow you to access your death benefit while alive for critical, chronic, or terminal illnesses.
- Using living benefits reduces the remaining death benefit, so the total policy amount must be sized accordingly.
- Independent brokers have access to multiple carriers, allowing for better comparison of rider pricing and terms.
- Captive agents can only offer riders from their single insurance company, which may limit your options.
- Carrier selection is crucial for applicants with health histories, as underwriting guidelines vary significantly.
- DG Life Group is an independent broker in Dallas with access to 30+ A-rated carriers.
- The base premium is the same regardless of the channel, but the rider premium can vary by carrier.
- Consulting with an independent broker ensures you are not missing out on favorable rider terms from other carriers.
Frequently Asked Questions
What is a living benefits rider?
A living benefits rider is an add-on to a life insurance policy that allows you to access a portion of the death benefit while you are still alive if you are diagnosed with a critical, chronic, or terminal illness.
Does using living benefits cancel my policy?
No, using living benefits does not cancel the policy. It reduces the remaining death benefit. For example, if you have a $500,000 policy and use 50% for a critical illness payout, the remaining death benefit for your beneficiaries will be $250,000.
Are living benefits tax-free?
In most cases, living benefits payouts are income-tax-free. However, tax laws can be complex, and you should consult with a tax professional for advice specific to your situation.
Why should I use an independent broker for living benefits?
Independent brokers can compare rider pricing and terms across multiple carriers. This allows them to find the most cost-effective and comprehensive living benefits coverage for your specific health profile.
How much does a living benefits rider cost?
The cost of a living benefits rider varies by carrier, age, health status, and the type of rider. It is typically a percentage of the base premium. An independent broker can provide specific quotes based on your profile.
Can I add living benefits to an existing policy?
In some cases, you can add riders to an existing policy, but this depends on the carrier and your current health status. It is often easier to select the riders when you first purchase the policy.
What is the difference between critical illness and chronic illness benefits?
Critical illness benefits provide a lump sum payment upon diagnosis of specific conditions like cancer or heart attack. Chronic illness benefits provide periodic payments if you become unable to perform daily living activities due to a chronic condition.
Conclusion
Selecting the right life insurance broker in Dallas for living benefits is a decision that can have a significant impact on your family's financial security. By choosing an independent broker like DG Life Group, you gain access to a wide range of carriers and the expertise needed to navigate the complexities of living benefits riders. This approach ensures that you are not limited to a single company's options and can find the most favorable terms for your specific needs.
If you are looking for life insurance with living benefits in Dallas, consider scheduling a consultation with DG Life Group. Their team can help you compare options from 30+ A-rated carriers and find the policy that best fits your life stage and health profile. Schedule a free call to start the conversation.