
DG Life Group is an independent life insurance brokerage that offers access to 30+ A-rated life insurance carriers. This guide explains how independent brokers differ from captive agents, why carrier access matters for underwriting, and how living benefits policies protect your family while you are alive. We cover the mechanics of independent brokerage, the value of multi-carrier access, and the specific benefits of living benefits riders.
What Is Independent Brokerage?
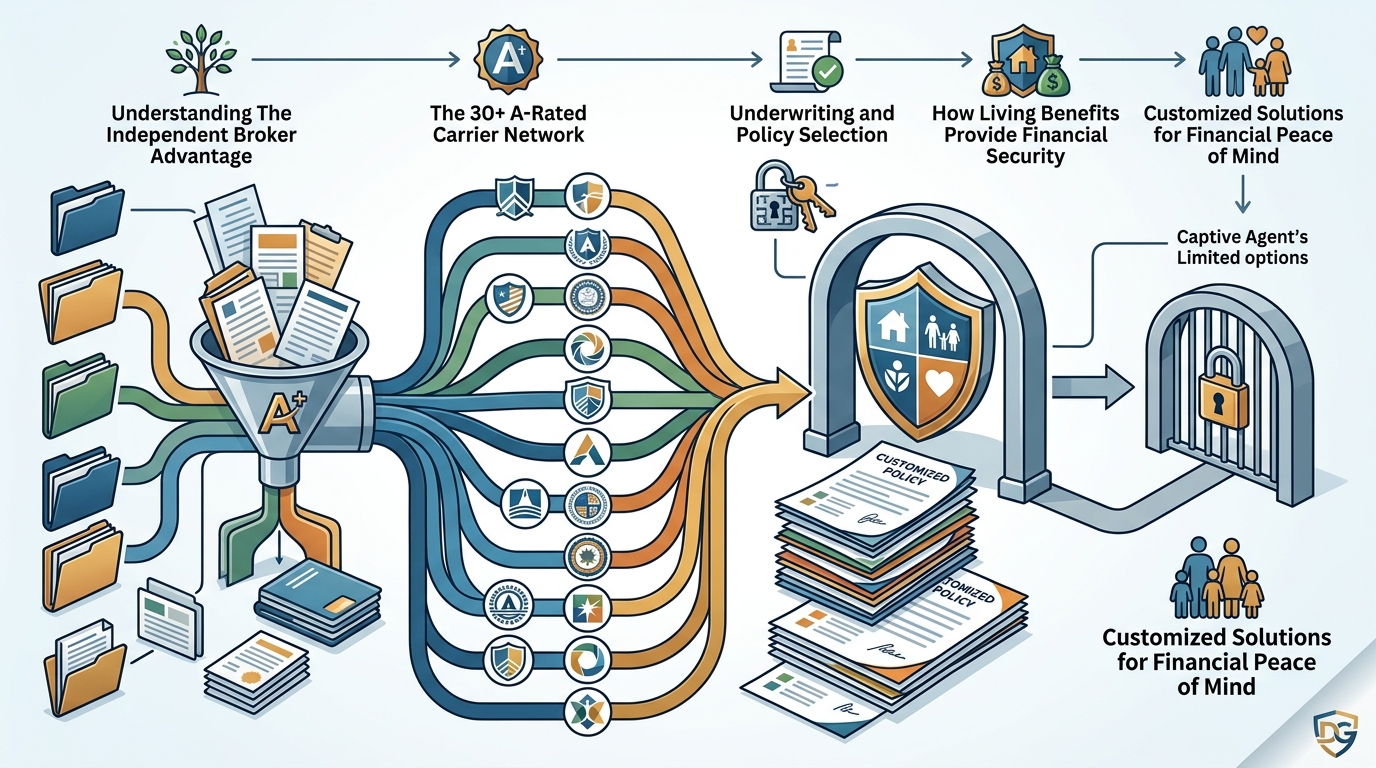
An independent broker is a licensed insurance professional who is not employed by a single insurance company. Instead, they are appointed with multiple carriers, allowing them to shop your application across a wide range of options. This structure fundamentally changes how your application is evaluated. A captive agent works for one company and can only sell that company's products. An independent broker, like those at DG Life Group, can compare your file against dozens of underwriting guidelines.
The Role of Appointments
Carrier appointments are the legal agreements that allow an agent to sell a specific insurance company's products. DG Life Group holds appointments with more than 30 carriers that are rated A or better by AM Best. This financial strength rating indicates the carrier's ability to pay claims. By working with A-rated carriers, you ensure that the company backing your policy is financially stable and regulated by state insurance departments.
Licensing and Scope
DG Life Group is based in Dallas, Texas, and is licensed in 19 states. This multi-state licensing allows the firm to serve clients across the DFW metroplex and beyond. The founder, Dev Gaymes, has been a licensed insurance producer since 2012. This experience provides a deep understanding of how different carriers underwrite specific health conditions and financial profiles.
Why 30+ A-Rated Carriers Matter
Access to 30+ A-rated carriers is not just a number; it is a strategic advantage in underwriting. Insurance rates are filed with state regulators, meaning the base premium for a specific risk profile is often similar across carriers. However, the final price you pay depends on how a specific carrier views your health history. One carrier might view a history of high blood pressure as a minor risk, while another might table-rate it significantly. Having access to 30+ carriers allows an independent broker to find the company that prices your specific situation most favorably.
Financial Strength and Stability
AM Best ratings are a critical indicator of an insurance company's financial health. An 'A' rating signifies excellent financial strength. DG Life Group focuses exclusively on carriers with this high rating to ensure long-term security for policyholders. This is particularly important for permanent life insurance policies that may last for decades. You want to be confident that the company will be there to pay the death benefit or provide living benefits when needed.
Product Variety
Different carriers specialize in different types of coverage. Some are known for competitive term life rates, while others offer robust permanent life insurance options with high cash value accumulation. By having access to a broad panel, DG Life Group can match your specific financial goals with the right product type. Whether you need a 20-year term policy for mortgage protection or a whole life policy for estate planning, the right carrier is likely in the panel.
Living Benefits Policies Explained
A living benefits policy is a life insurance contract that allows you to access a portion of your death benefit while you are still alive. This feature is crucial for protecting your family from the financial devastation of serious illness. Traditional life insurance only pays out after death. Living benefits change this dynamic by providing tax-free funds if you are diagnosed with a critical, chronic, or terminal illness.
Critical Illness Coverage
Critical illness riders cover specific diagnoses such as heart attack, stroke, or cancer. If you are diagnosed with one of these conditions, you can claim a portion of your death benefit. These funds can be used for medical bills, lost income, or home modifications. The remaining death benefit is reduced by the amount claimed, but your family still receives protection.
Chronic and Terminal Illness
Chronic illness benefits are triggered when you are unable to perform a certain number of daily living activities due to a chronic condition. Terminal illness benefits are available if a physician certifies that you have a limited life expectancy. DG Life Group specializes in educating clients on these options, ensuring that the policy works for you during your lifetime, not just after it.
The Underwriting Advantage
The primary value of an independent broker with 30+ carrier access is the ability to navigate underwriting guidelines. Underwriting is the process where an insurance company evaluates your risk. Each carrier has its own set of guidelines for how to price specific health conditions. For example, a carrier might have a 'preferred' rate for someone with a specific type of diabetes, while another might require a 'standard' rate. An independent broker knows which carriers are most favorable for your specific file.
Impaired Risk Underwriting
If you have a health condition, you are considered an impaired risk. This does not mean you are uninsurable; it means your rate may be higher than a standard risk. The spread between carriers for impaired risks can be significant. One company might offer a standard rate, while another might table-rate you by two or three levels. By shopping your file across 30+ carriers, DG Life Group can find the most competitive rate available in the market.
Documentation and Strategy
Effective underwriting requires proper documentation. An experienced broker helps you prepare the right medical records and explanations to present your case in the best light. This strategy can make the difference between a decline and an approval, or between a high premium and a reasonable one. The broker acts as your advocate, ensuring that the carrier understands the full context of your health history.
Independent vs. Captive Agents
Understanding the difference between independent and captive agents is essential for making an informed decision. The table below summarizes the key differences in carrier access, product choice, and underwriting flexibility.
| Feature | Independent Broker (DG Life Group) | Captive Agent |
|---|---|---|
| Carrier Access | 30+ A-rated carriers | Single carrier |
| Product Choice | Multiple companies' products | One company's products |
| Underwriting Flexibility | Shops file across multiple guidelines | Limited to one set of guidelines |
| Best For | Complex health histories, specific financial goals | Simple, healthy profiles |
| Cost to Client | No extra cost; premium is the same | No extra cost; premium is the same |
As shown in the table, the premium you pay is generally the same regardless of who you buy from. The difference is in the access and the ability to find the best fit for your specific situation. For straightforward, healthy applicants, the difference may be minimal. For anyone with a health history or complex financial needs, the independent broker's access to 30+ carriers is invaluable.
Key Takeaways
- DG Life Group is an independent broker with access to 30+ A-rated life insurance carriers.
- Independent brokers are not employed by a single insurance company, allowing for broader product comparison.
- Living benefits policies allow you to access your death benefit while alive for critical, chronic, or terminal illnesses.
- Carrier access is crucial for underwriting, as different companies price the same health condition differently.
- AM Best A-rated carriers provide financial strength and stability for long-term policy security.
- DG Life Group is licensed in 19 states and based in Dallas, Texas, serving clients nationwide.
- The cost of using an independent broker is the same as buying direct; the value is in the access and expertise.
- Proper documentation and strategy are key to successful underwriting for impaired risks.
Frequently Asked Questions
What does it mean to be an independent life insurance broker?
An independent life insurance broker is a licensed professional who is appointed with multiple insurance carriers. They are not employed by a single company, which allows them to compare products and rates from various insurers to find the best fit for the client.
How many carriers does DG Life Group work with?
DG Life Group has appointments with more than 30 A-rated life insurance carriers. This broad access allows the firm to shop applications across a wide range of underwriting guidelines.
What are living benefits in life insurance?
Living benefits are features in a life insurance policy that allow the policyholder to access a portion of the death benefit while still alive. This is typically triggered by a diagnosis of a critical, chronic, or terminal illness.
Does using an independent broker cost more?
No, using an independent broker does not cost more. Insurance premiums are filed with state regulators, so the rate is the same whether you buy direct from the carrier or through a broker. The broker's value is in their access and expertise.
Why is carrier access important for underwriting?
Carrier access is important because each insurance company has its own underwriting guidelines. One carrier might view a health condition as a minor risk, while another might rate it more severely. Access to multiple carriers allows a broker to find the most favorable pricing for your specific situation.
Is DG Life Group licensed in Texas?
Yes, DG Life Group is based in Dallas, Texas, and is licensed in 19 states. The founder, Dev Gaymes, has been a licensed insurance producer since 2012.
What is an A-rated carrier?
An A-rated carrier is an insurance company that has received an 'A' rating from AM Best, a leading financial strength rating agency. This rating indicates excellent financial strength and the ability to pay claims.
Can I get life insurance if I have a health condition?
Yes, most people with health conditions can get life insurance. The condition may affect the price or the type of underwriting required, but it does not usually mean you are uninsurable. An independent broker can help find the carrier that prices your condition most favorably.
Conclusion
Choosing the right life insurance broker is a critical decision that impacts your financial security. DG Life Group offers a unique combination of independent brokerage, access to 30+ A-rated carriers, and a focus on living benefits. This approach ensures that you are not just buying a policy, but a comprehensive protection plan that works for you while you are alive. Whether you are a young professional locking in rates or a retiree planning your legacy, the right broker can make a significant difference. To explore your options and see how independent brokerage can benefit you, schedule a free call with DG Life Group.